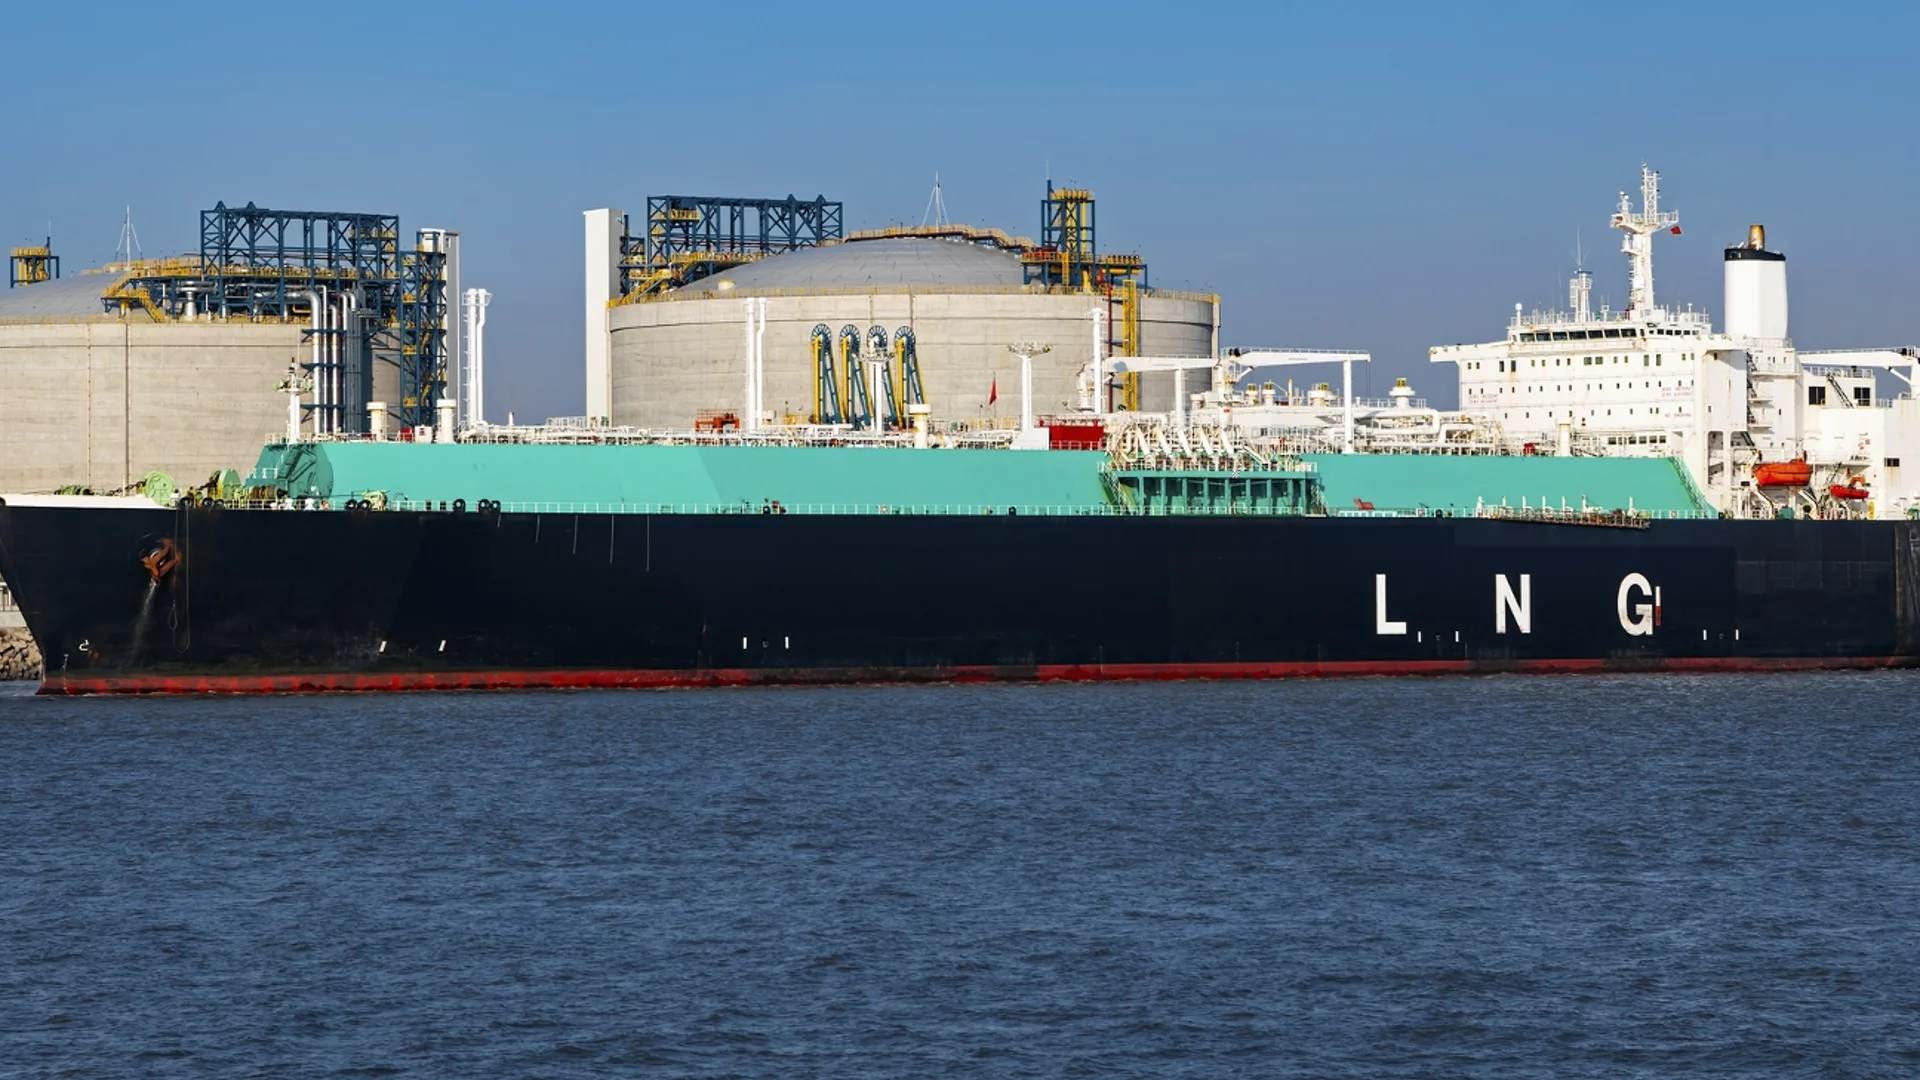
The logistical damage is profound. Despite occasional, clandestine shipments, LNG flows through the Strait remain over 75% below pre-war levels. Unlike crude oil, which producers have successfully redirected through ship-to-ship transfers, LNG is tethered to specialized liquefaction infrastructure. Saad Sherida Al-Kaabi, CEO of QatarEnergy, confirmed that the lack of pipeline alternatives makes any rapid pivot impossible. Furthermore, March strikes on the Ras Laffan complex damaged two critical liquefaction trains, with repairs expected to consume three years.
This supply vacuum has forced a brutal recalibration of global energy markets. Asian spot prices and European benchmarks have surged to 2023 highs, hitting price-sensitive economies in South Asia particularly hard. Wood Mackenzie analysts now project a 6 million tonne collapse in South Asian demand, a sharp reversal from earlier growth forecasts. While the European Commission maintains that the EU’s diversified import network is better prepared for winter than in 2021, storage levels remain historically low at 73%. With QatarEnergy extending force majeure declarations through November, even an immediate reopening of the Strait would arrive too late to stabilize supply chains for the peak heating season.


Comments (0)
No comments yet. Be the first!