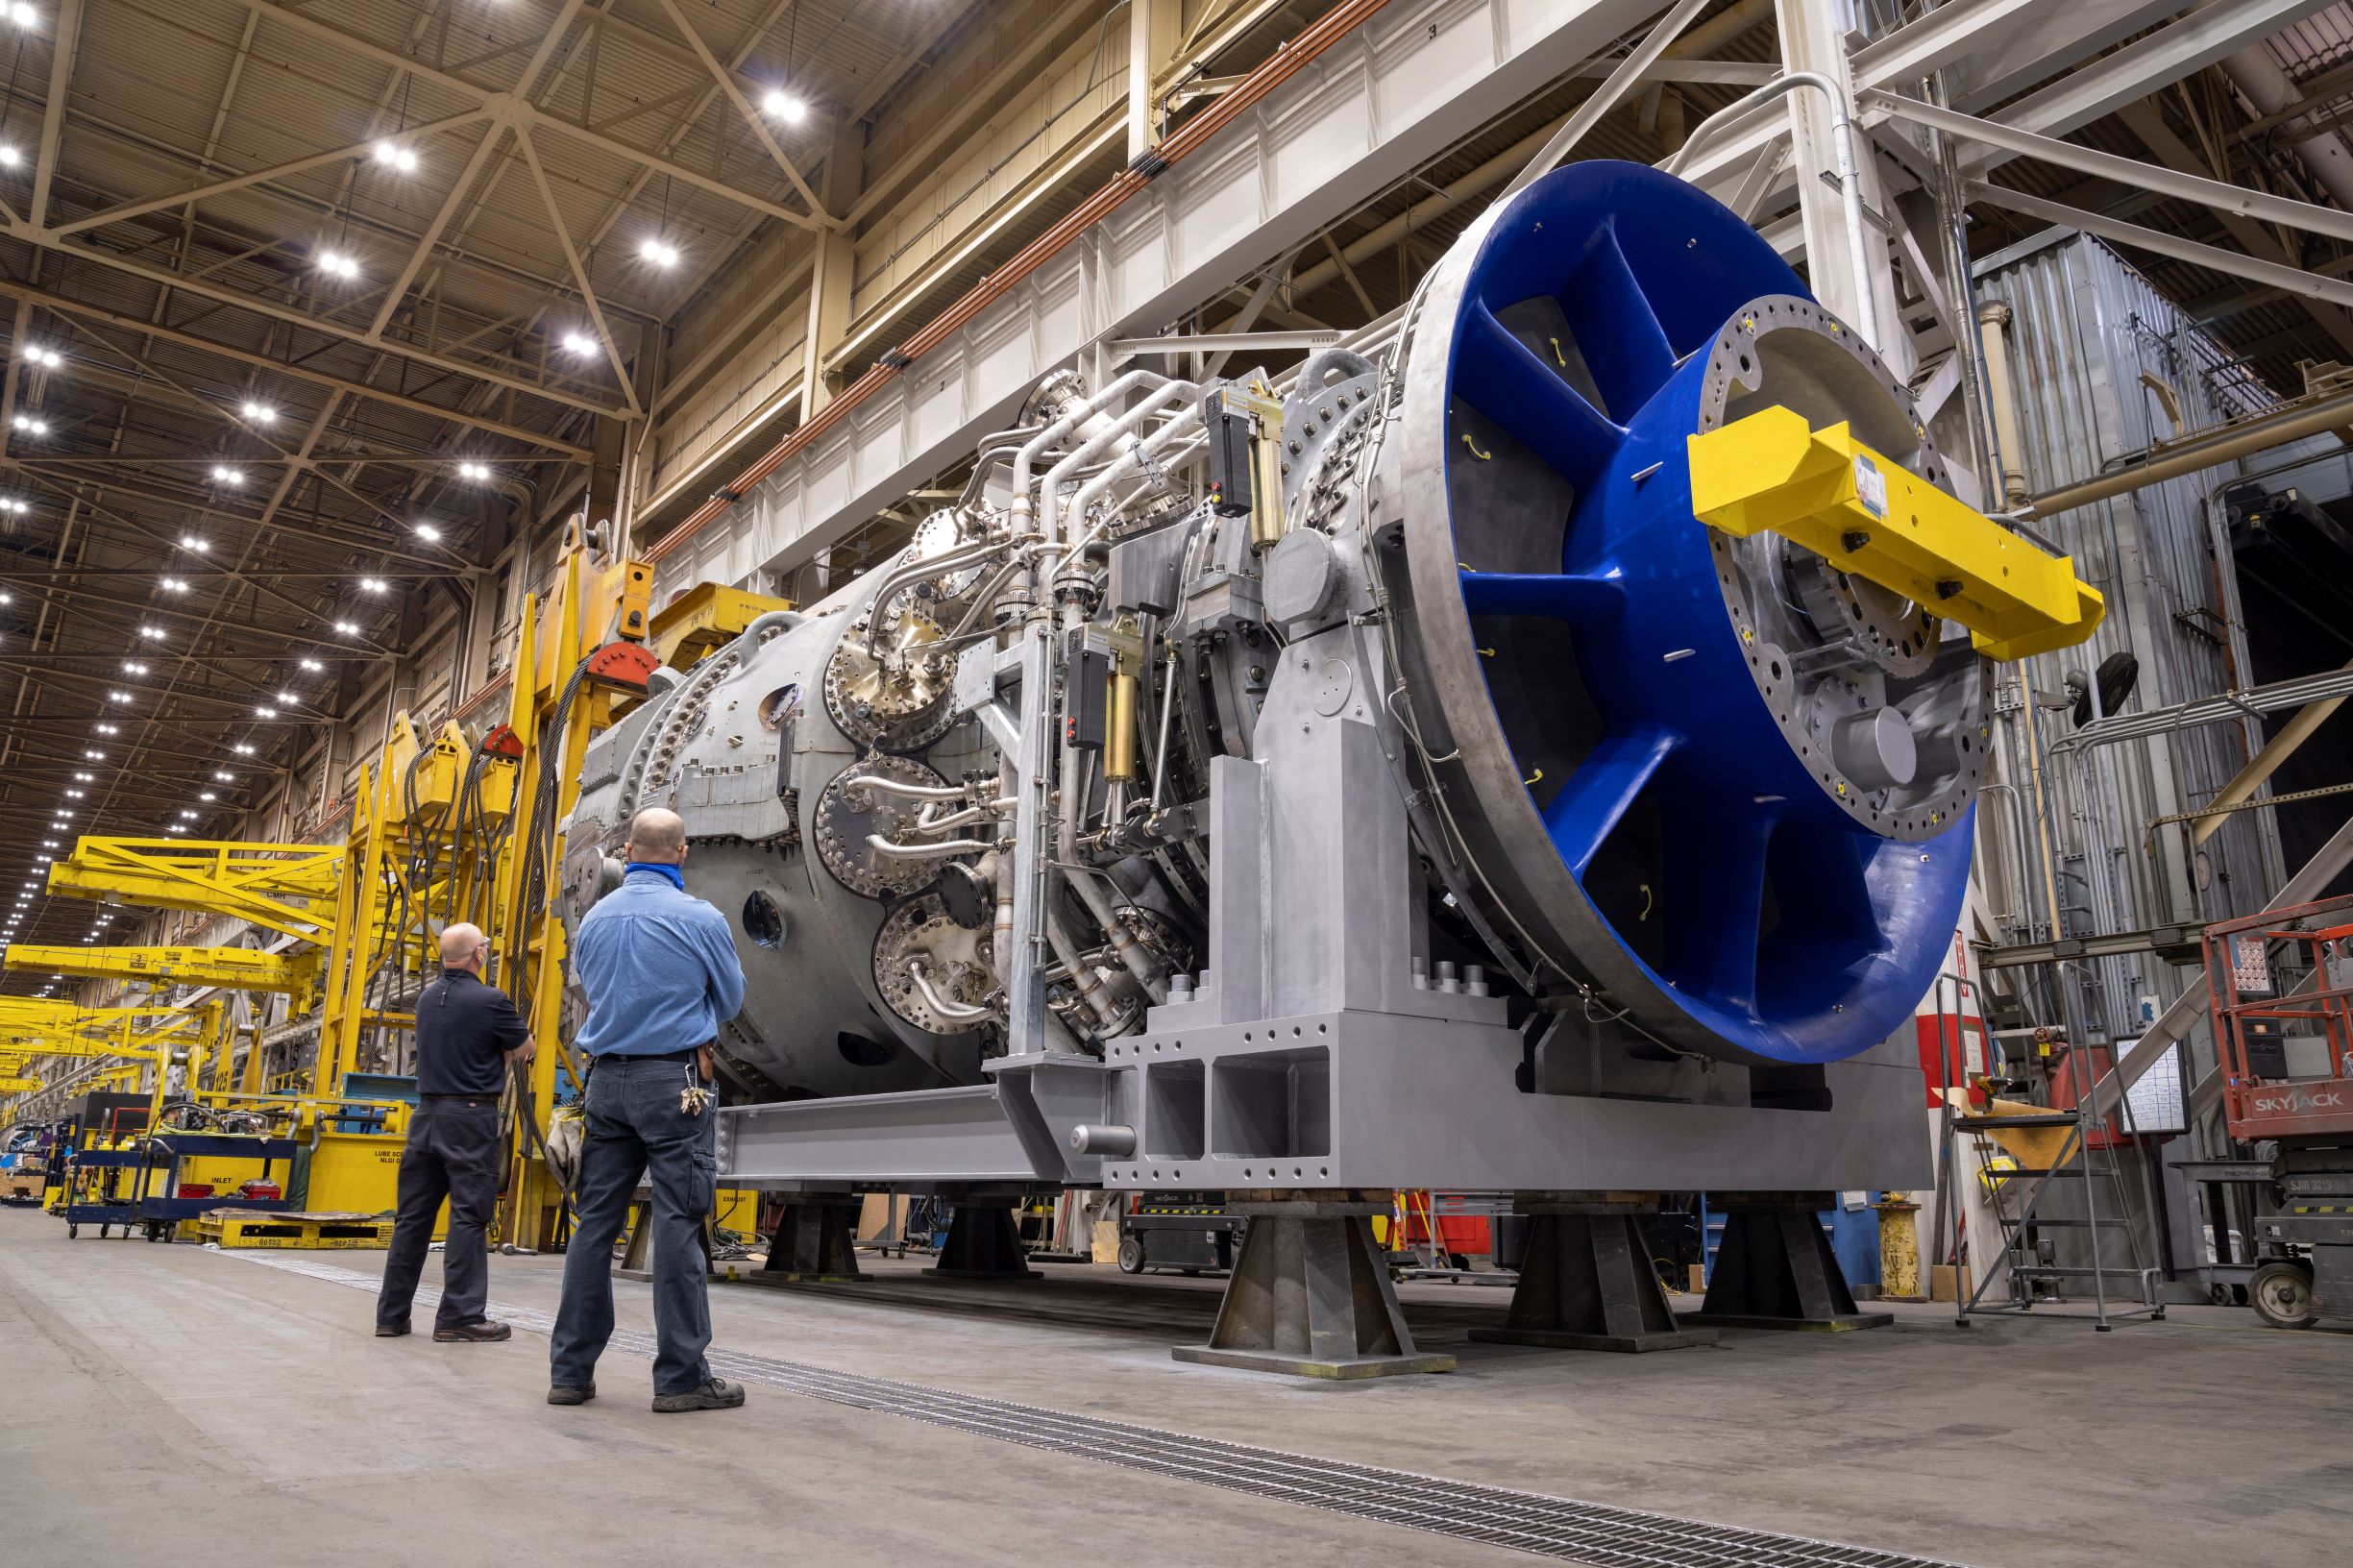
GE Vernova remains the most prominent proxy for the power crunch, carrying a $176 billion backlog that dwarfs its annual revenue. While its gas turbine business faces a multi-year waiting list, the company’s wind division continues to weigh on margins. Investors are watching for signs that production is scaling beyond current limits and whether recent frame agreements with Venture Global provide the expected long-term stability.
Eaton and Quanta Services are taking aggressive, distinct paths to secure their supply chains. Eaton has deployed over $11 billion in acquisitions to capture thermal management and enclosure capacity, though the resulting debt load and restructuring costs have clouded its recent GAAP earnings. Meanwhile, Quanta has moved from installation to manufacturing through a joint venture for circuit breakers, signaling a shift toward vertical integration to bypass industry-wide bottlenecks. Elsewhere, Powell Industries is riding a surge in utility-scale demand, though Fluence Energy faces significant execution hurdles. The latter’s struggle to ramp up its Houston battery facility underscores a broader industry risk: even with record demand from hyperscalers, the transition from order to delivery remains a complex, capital-intensive challenge for manufacturers.



Comments (0)
No comments yet. Be the first!