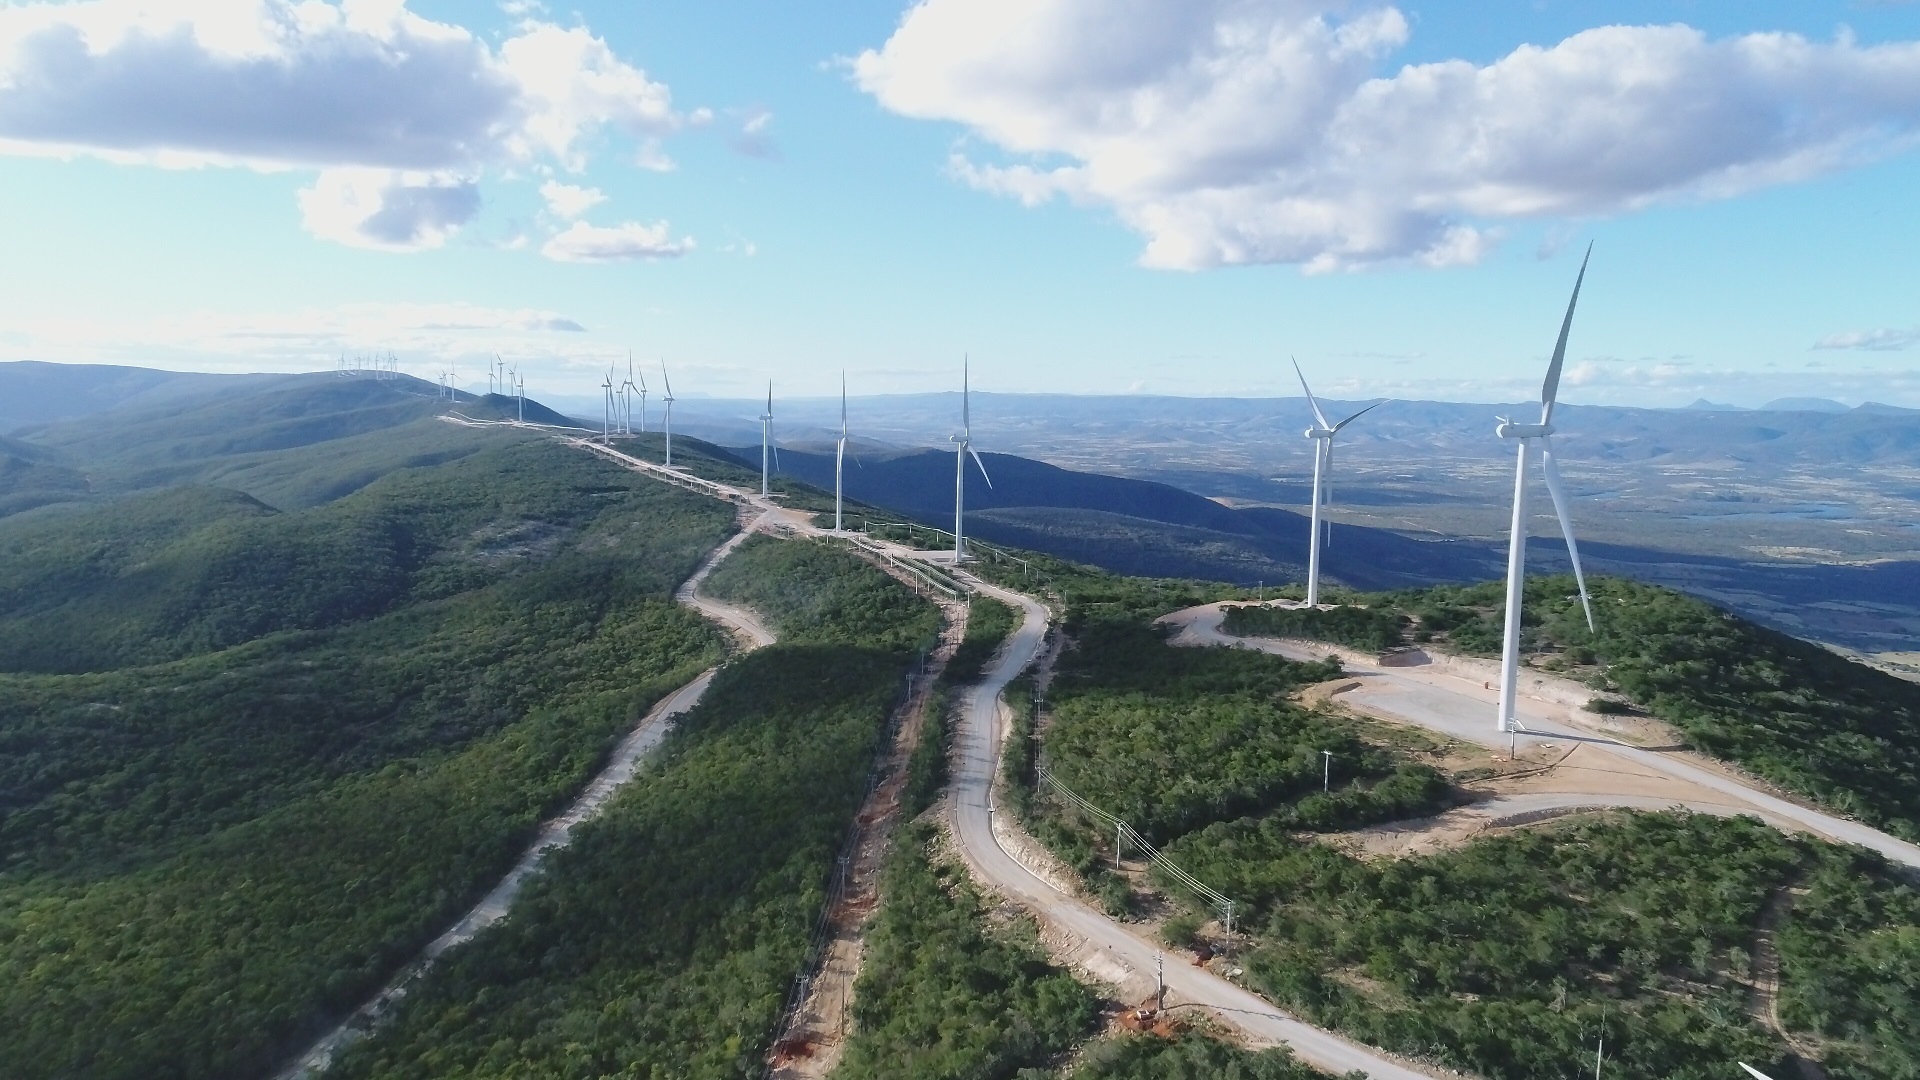
The path toward this goal faces immediate physical realities. While installed capacity climbed past 44.7 GW in 2022, current infrastructure struggles to keep pace with project development. Wood Mackenzie analyst Kárys Prado notes that power oversupply and grid restrictions are creating headwinds in established markets like Brazil and Chile, where fierce competition from the solar sector further complicates growth trajectories.
Brazil remains the dominant player, holding 35 GW of commercial onshore wind capacity—the fifth-largest footprint globally. Most of this generation is clustered in the northeast, exemplified by Statkraft’s Ventos de Santa Eugênia complex in Bahia. Meanwhile, Mexico is recalibrating its strategy. Following years of stagnation under nationalization policies, the government now seeks to attract private participation to reach a target of 30 GW in new renewable and storage capacity by 2030. BloombergNEF projects that Mexico could see $630 billion in new power asset investment through 2035.
Argentina is also moving to modernize its grid, with the International Finance Corporation backing the new Olavarria Wind Farm. This project, linked to the Bahía Blanca-Abasto transmission corridor, represents a shift toward privately financed infrastructure integrated into the national system. As these nations refine their regulatory frameworks, the success of the regional green transition will ultimately depend on whether grid expansion can outpace the surge in new generation.
Comments (0)
No comments yet. Be the first!