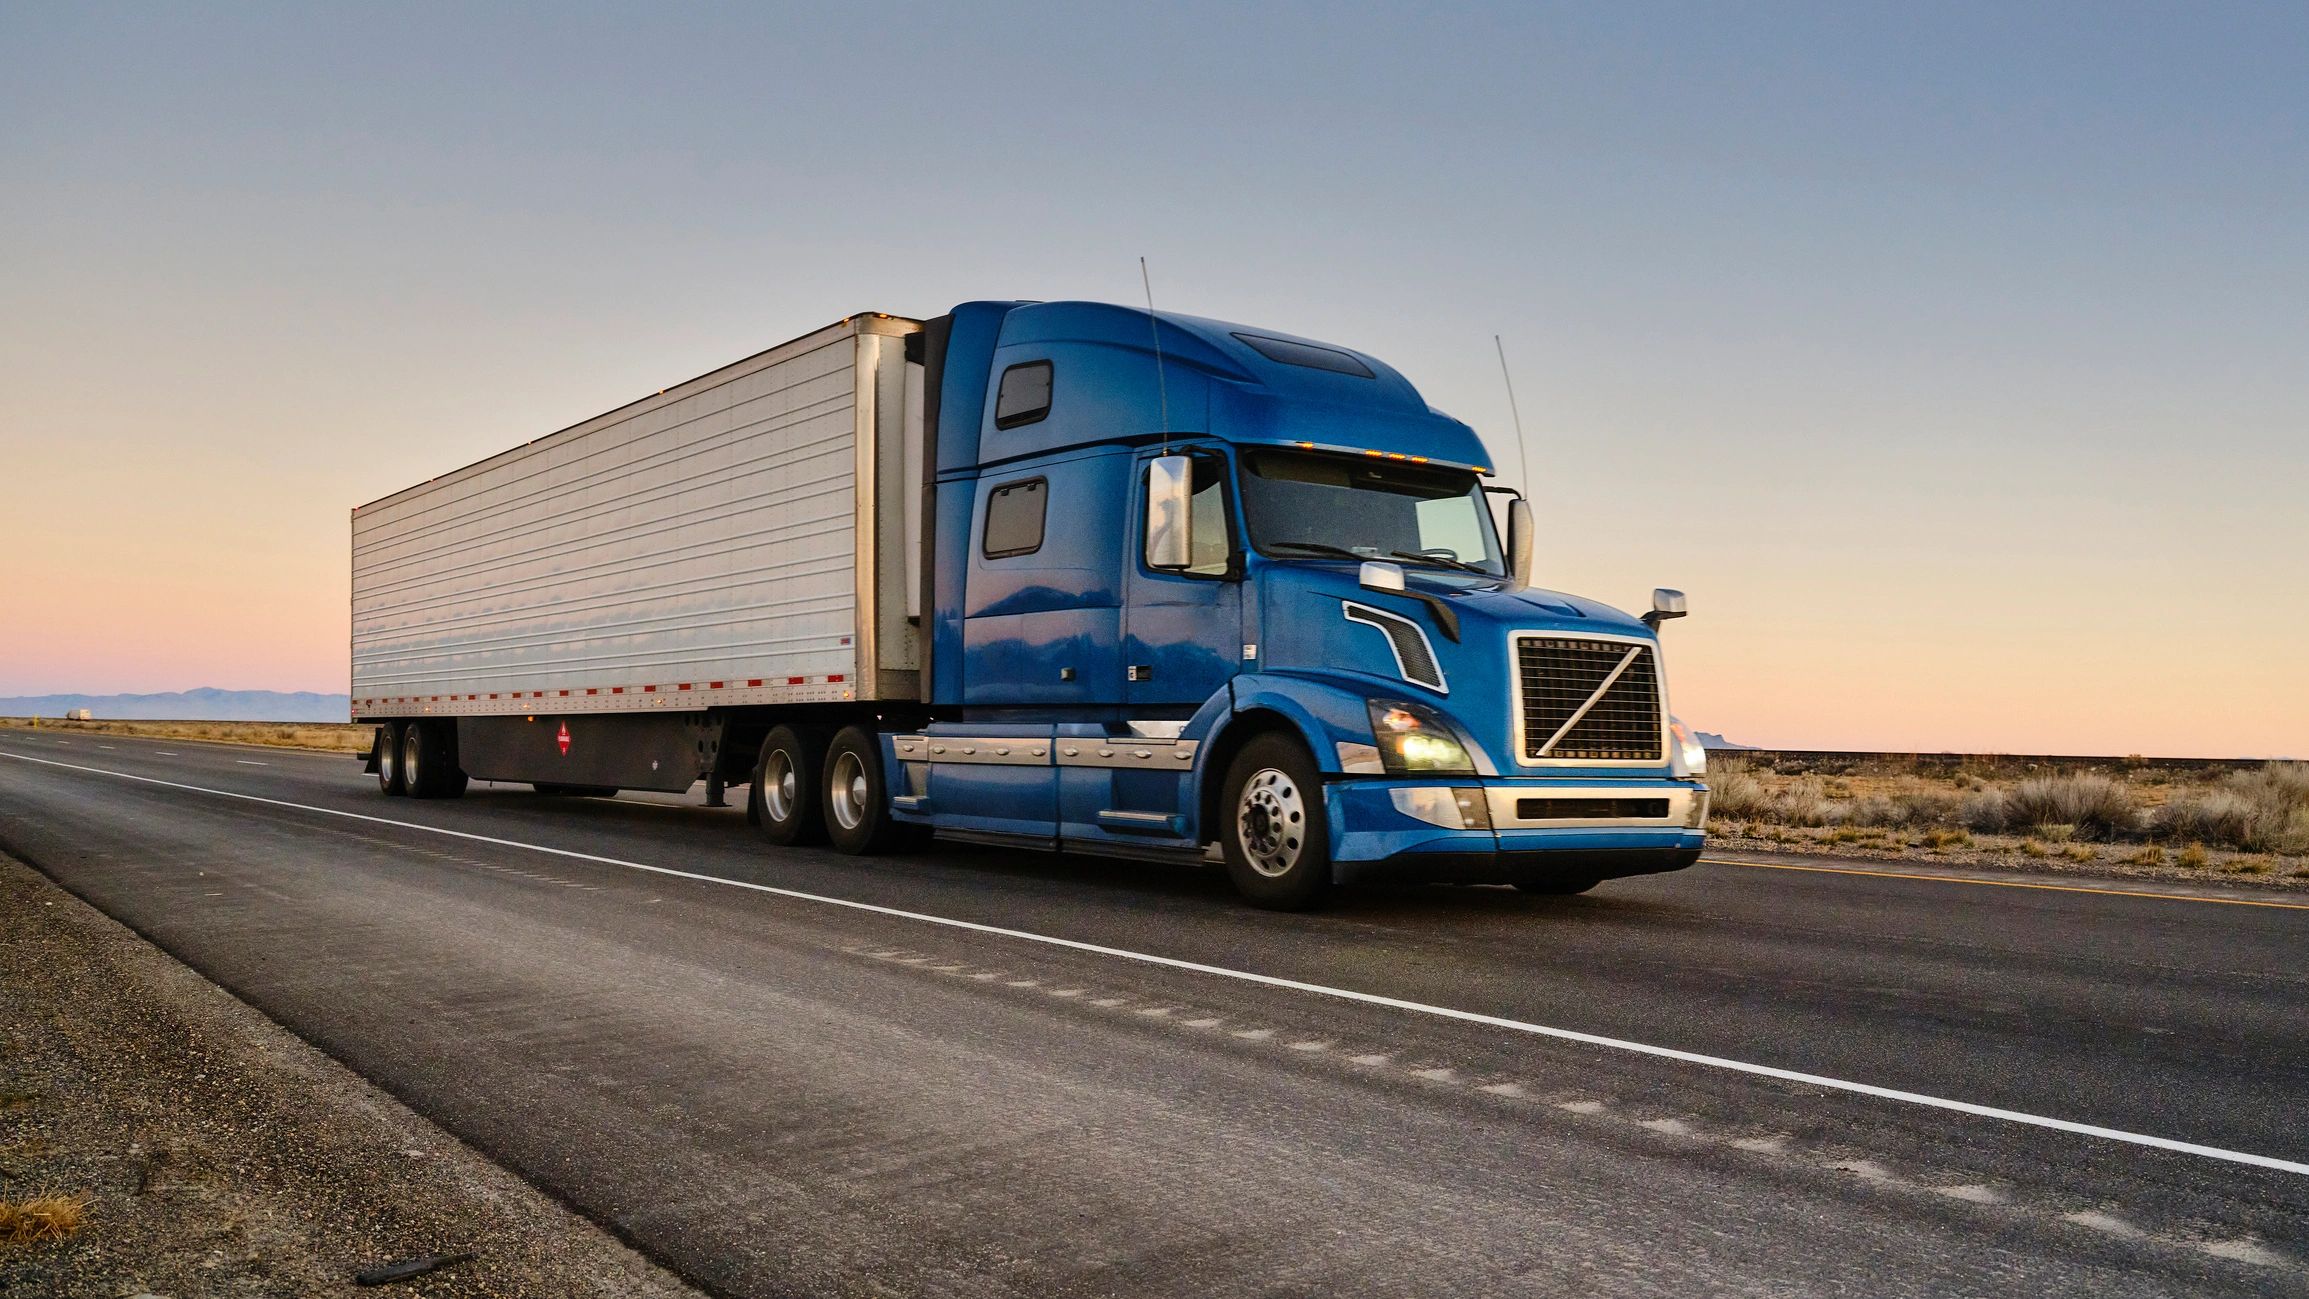
The transportation landscape for the final quarter of 2026 is defined by structural cost increases that show little sign of softening. Parcel shipping, in particular, is experiencing a perfect storm where fuel surcharges have evolved from simple pass-through costs into permanent revenue levers for carriers. AFS Logistics data reveals that even if fuel prices were to crash, current surcharge tables ensure rates remain roughly three times higher than they were in early 2021. Adding to the burden, FedEx is set to reclassify over 2,500 ZIP codes into more expensive remote delivery tiers starting January 2027.
In the truckload and LTL sectors, the dynamic is driven by a supply-side crunch. Despite soft demand and declining tonnage, carriers are maintaining tight control over pricing. Truckload rates are climbing toward levels not seen since early 2022, fueled by regulatory pressures that are thinning the pool of available drivers and trucks. Meanwhile, LTL rates have eclipsed 80% above their 2018 baseline, marking the third consecutive quarter of record-setting pricing. For shippers, this environment necessitates a delicate balancing act, as they juggle carrier capacities and navigate surcharges that increasingly penalize any volume exceeding baseline projections.
Comments (0)
No comments yet. Be the first!